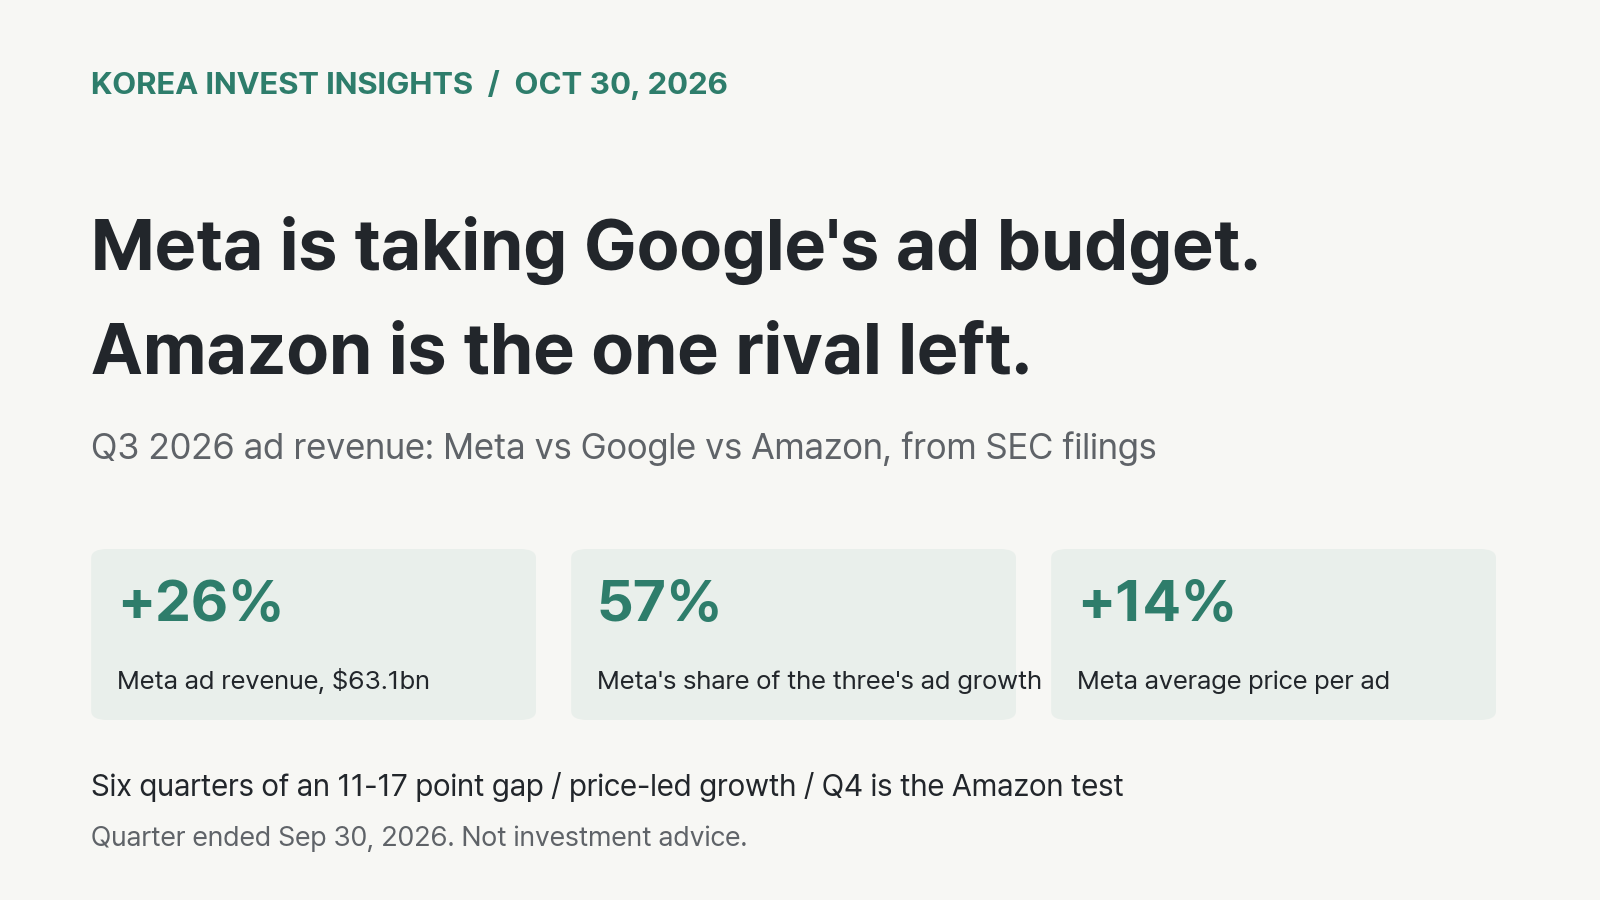
Meta's Q3 ad revenue grew 26%; Google's and Amazon's grew 11%. Meta has out-grown Google by 11-17 points for six straight quarters, and advertisers paid 14% more per Meta ad. Amazon is the rival Meta has not beaten yet.
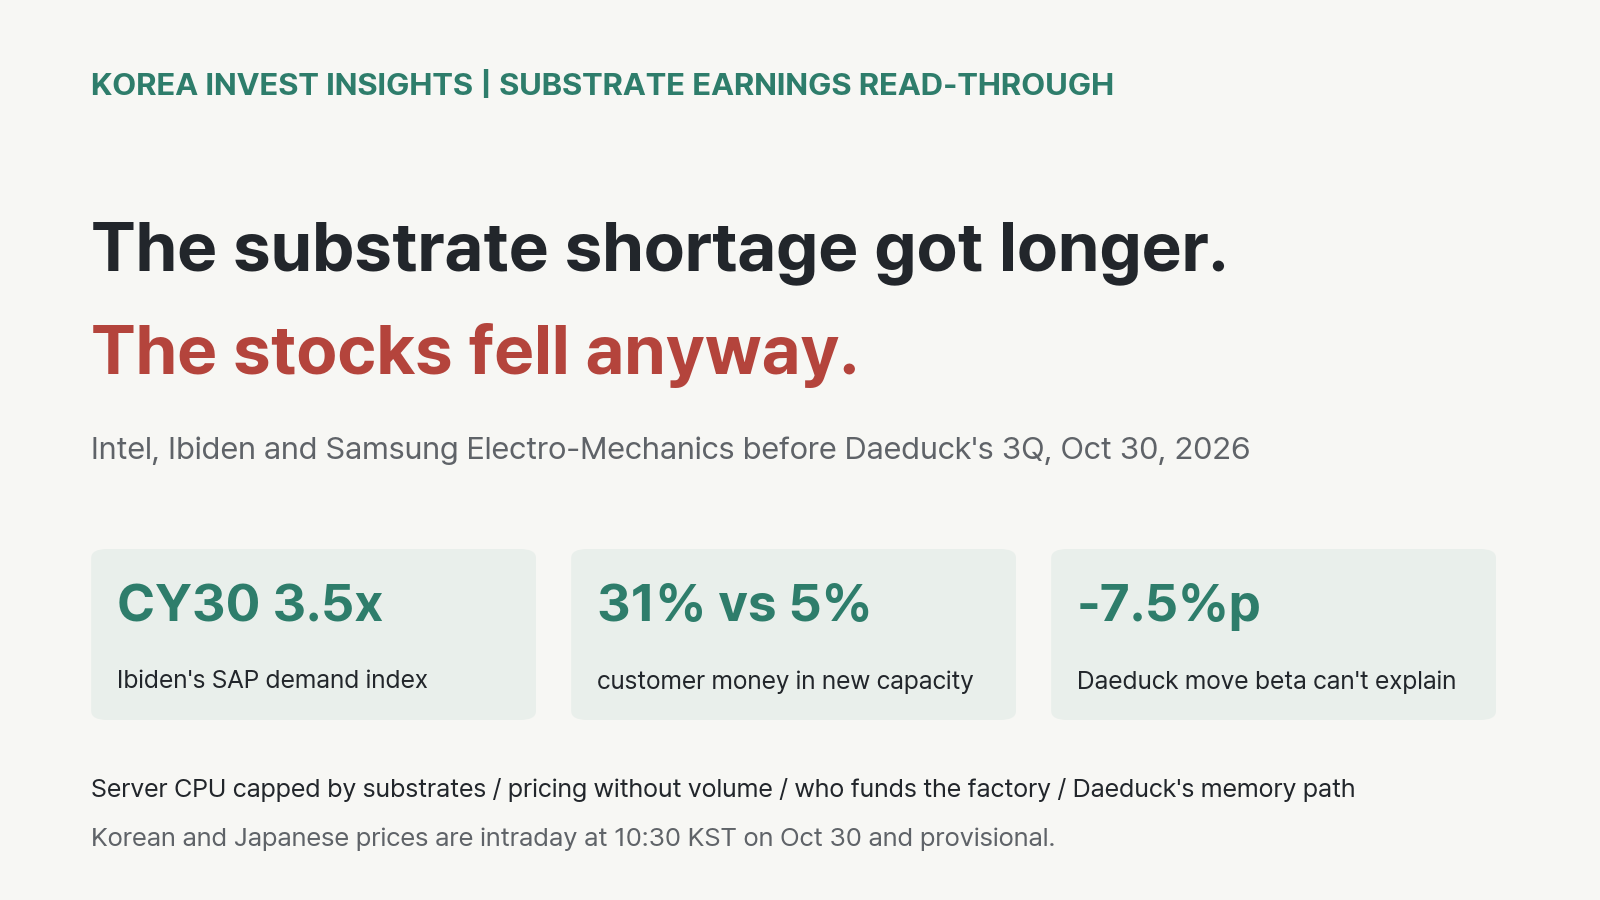
Intel says substrates cap its server CPUs. Ibiden sees demand far above supply to 2030. Yet Ibiden hit limit-down and SEMCO and Daeduck fell 9-13%. Before Daeduck's 3Q, we split the selling and ask who funds new capacity.
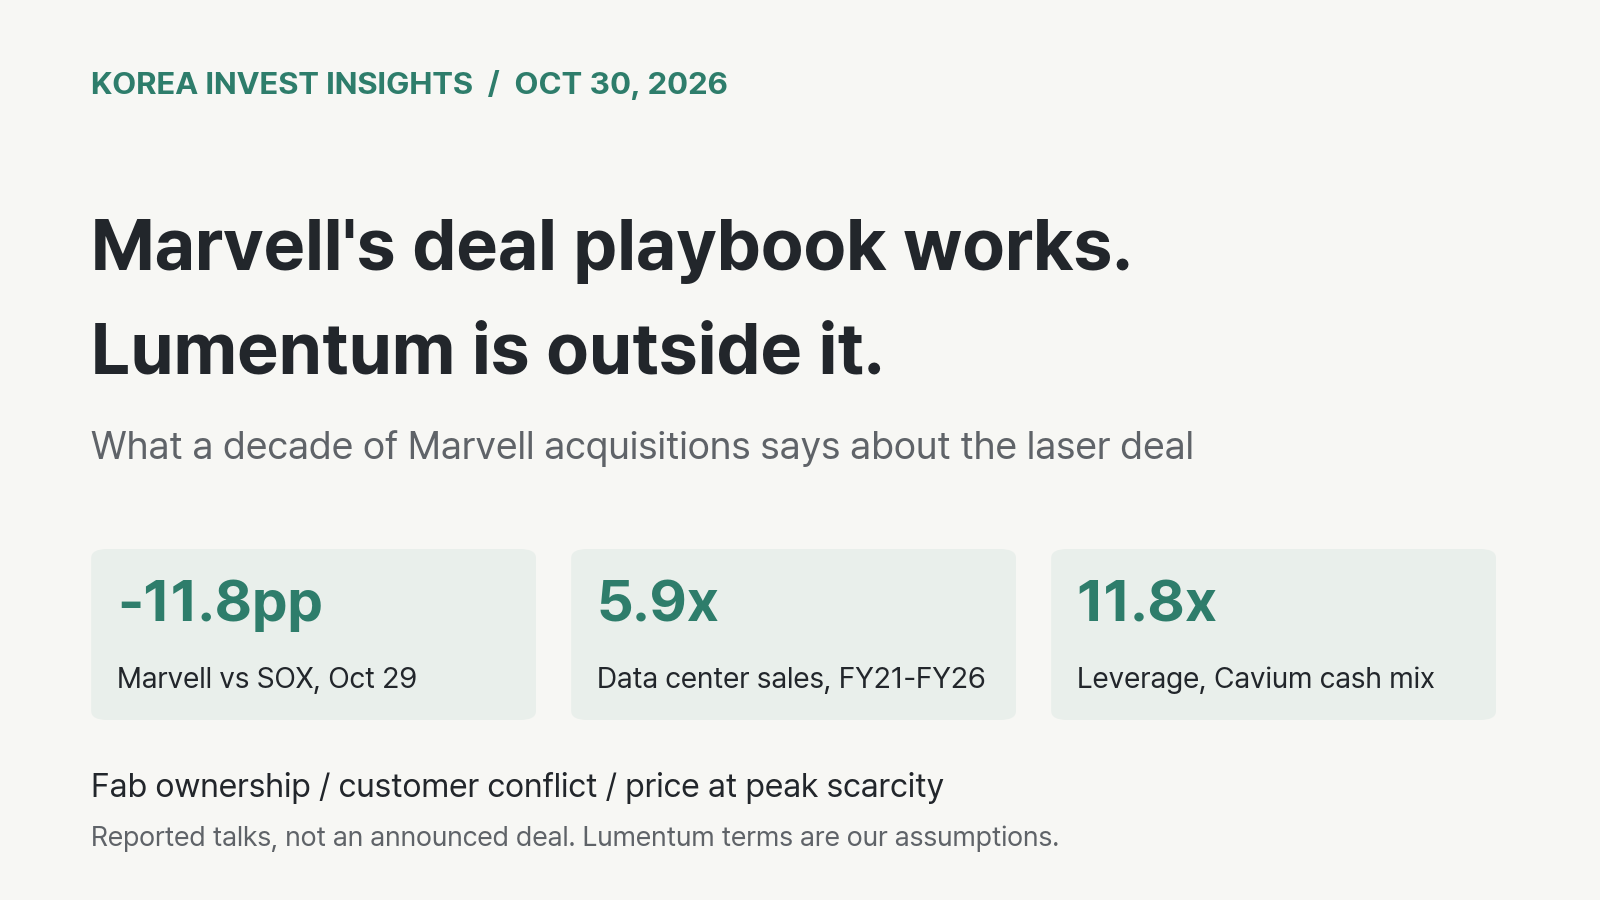
Marvell trailed chip stocks by 11.8 points on the Lumentum report. After its last two big deals, the first-day move and the one-year result went opposite ways. But its record is in fabless assets. Lumentum brings fabs and customer conflict.
KOSPI breadth collapses to 20.6% above 50-DMA as construction and renewables sell off. Daedeok, TFE, and Dongkuk Pharma lead today's quality re-rating screen.
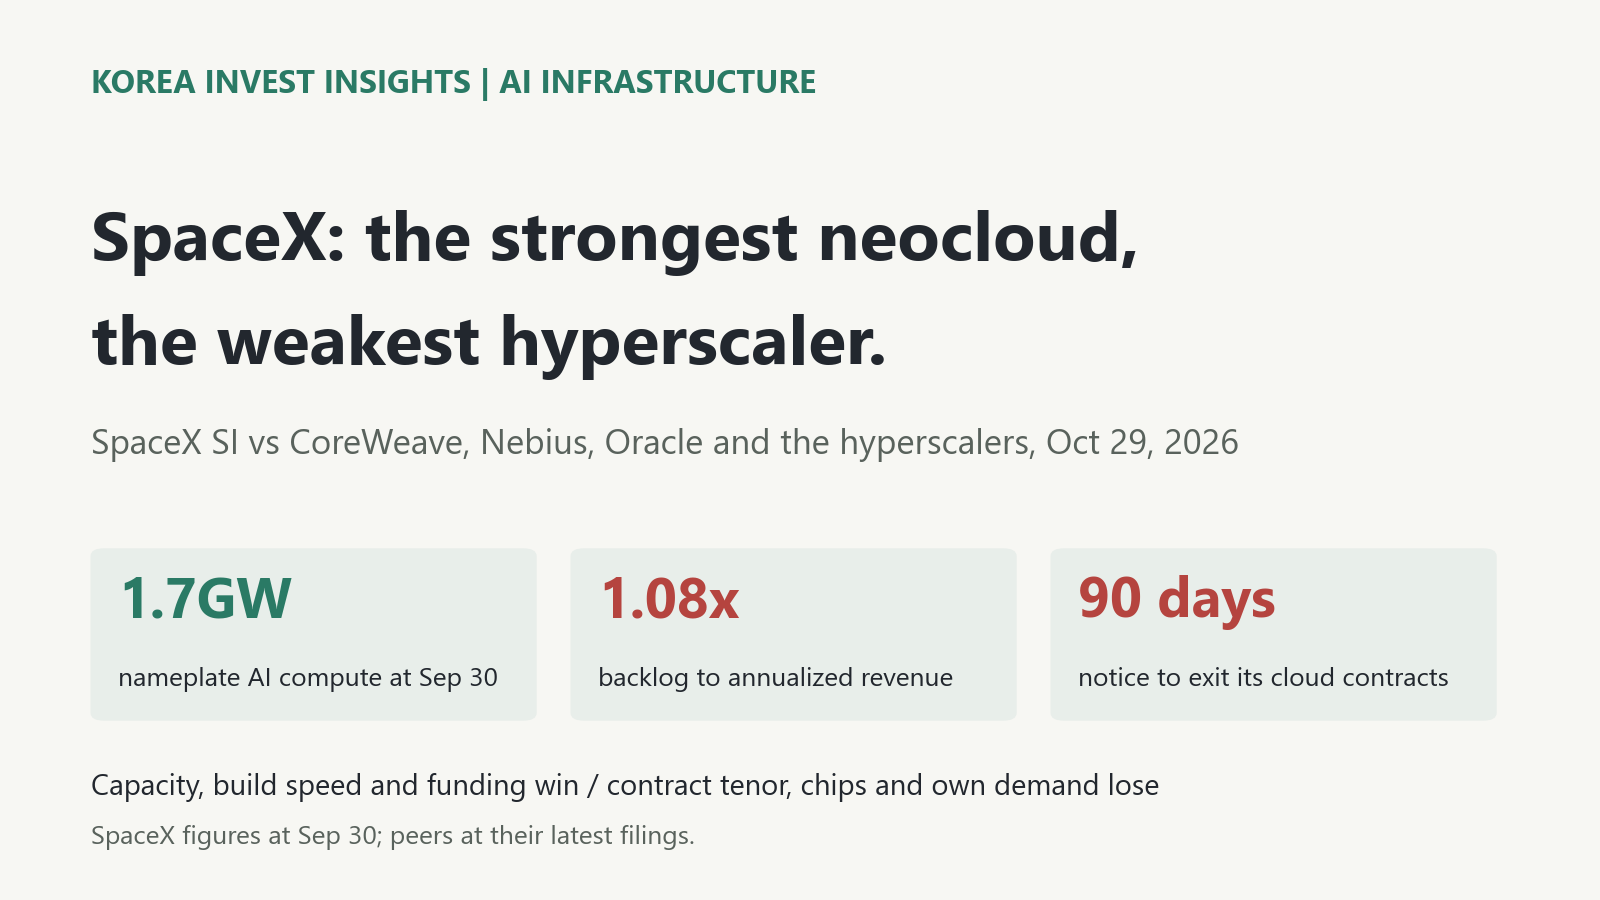
SpaceX's AI arm beats every neocloud on installed capacity, build speed and cost of debt. Against the hyperscalers it has the thinnest backlog, no chip of its own and cloud contracts either side can end on 90 days' notice. Its 65.5% margin is a scarcity price.
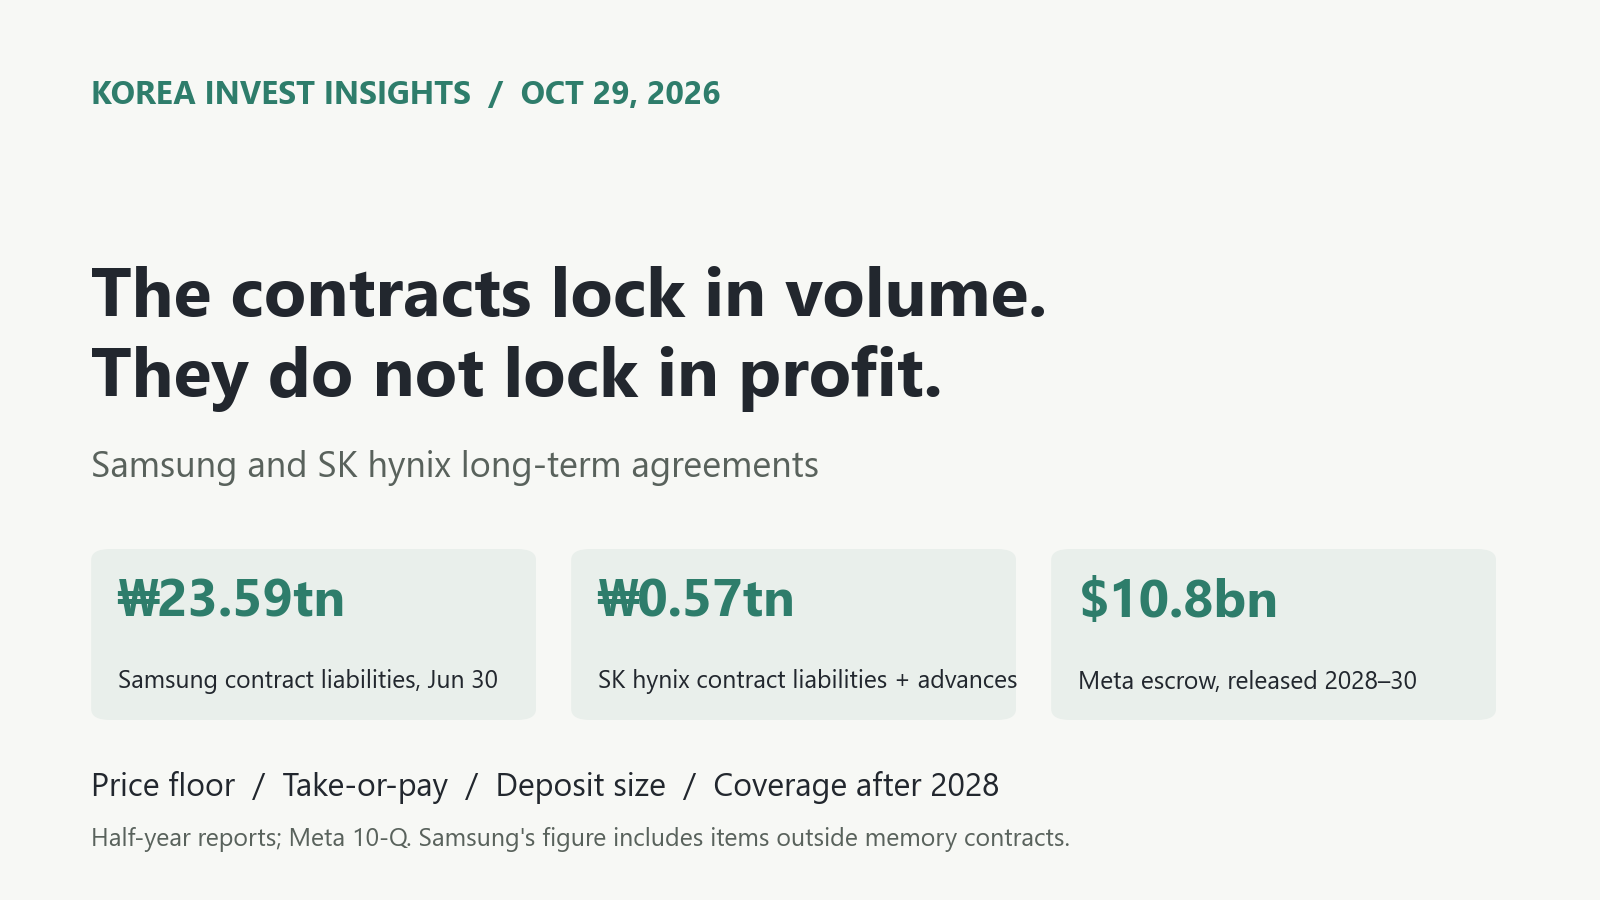
Samsung targets 60–70% of capacity under long-term contracts and SK hynix says it is effectively sold out through 2029. Their own filings, and Alphabet's CFO, say volume and price can still move. The contracts secure 2027–28 volume, not a profit floor.
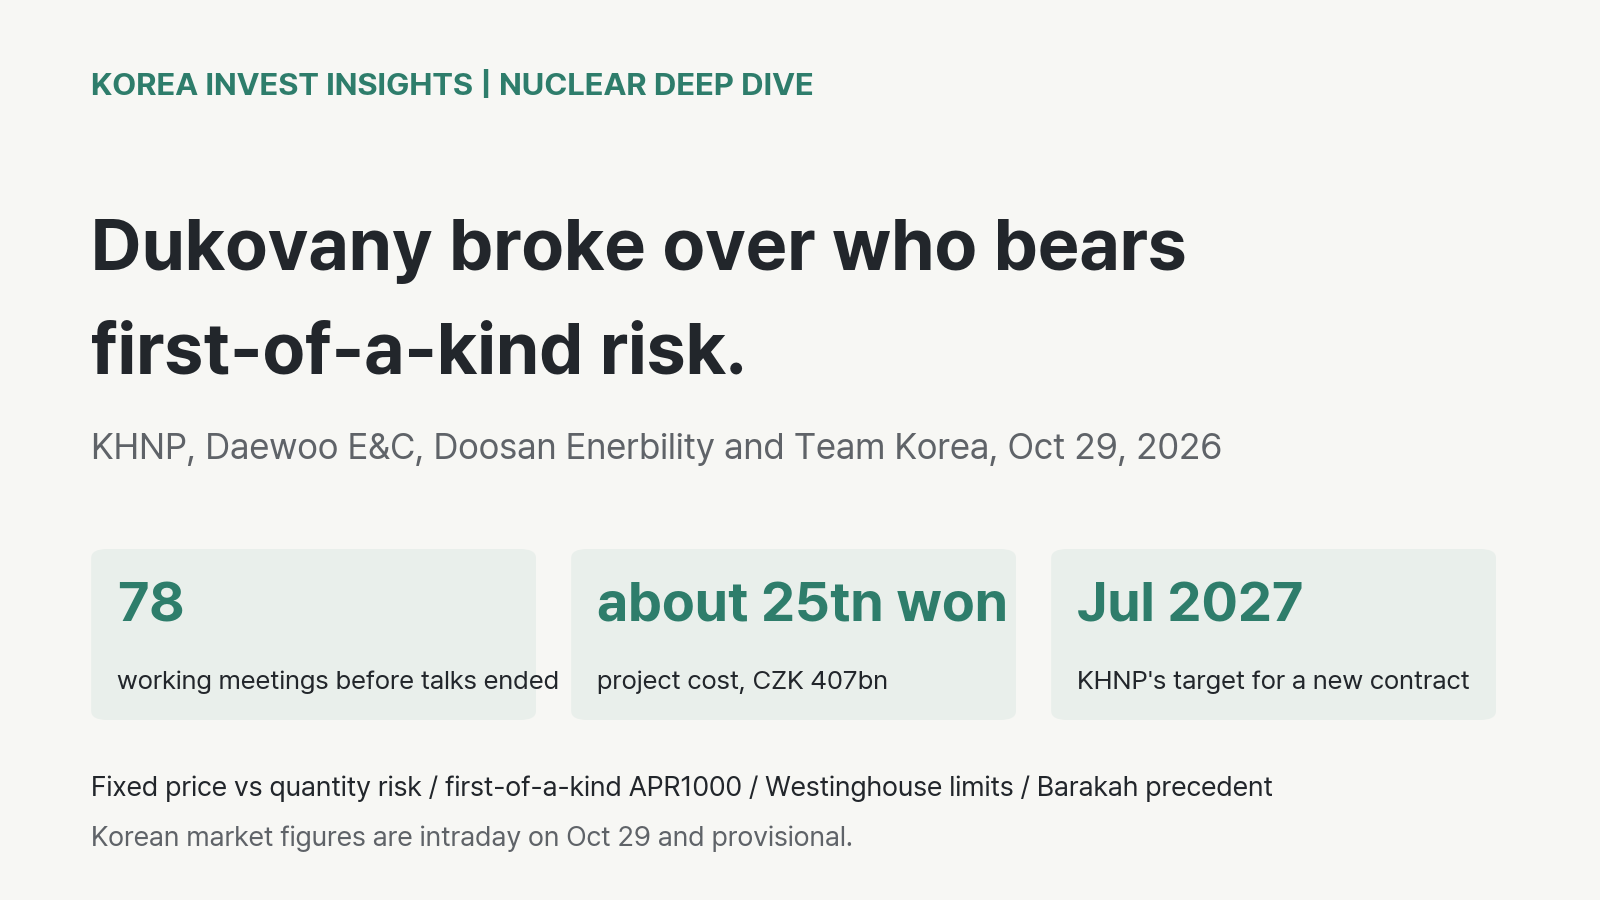
KHNP ended Dukovany building talks with Daewoo E&C and Doosan Enerbility and will name a new builder by July 2027. The main contract and Doosan's equipment deal stand. Four stocks closed 5.2tn won lower, far above the profit at stake.
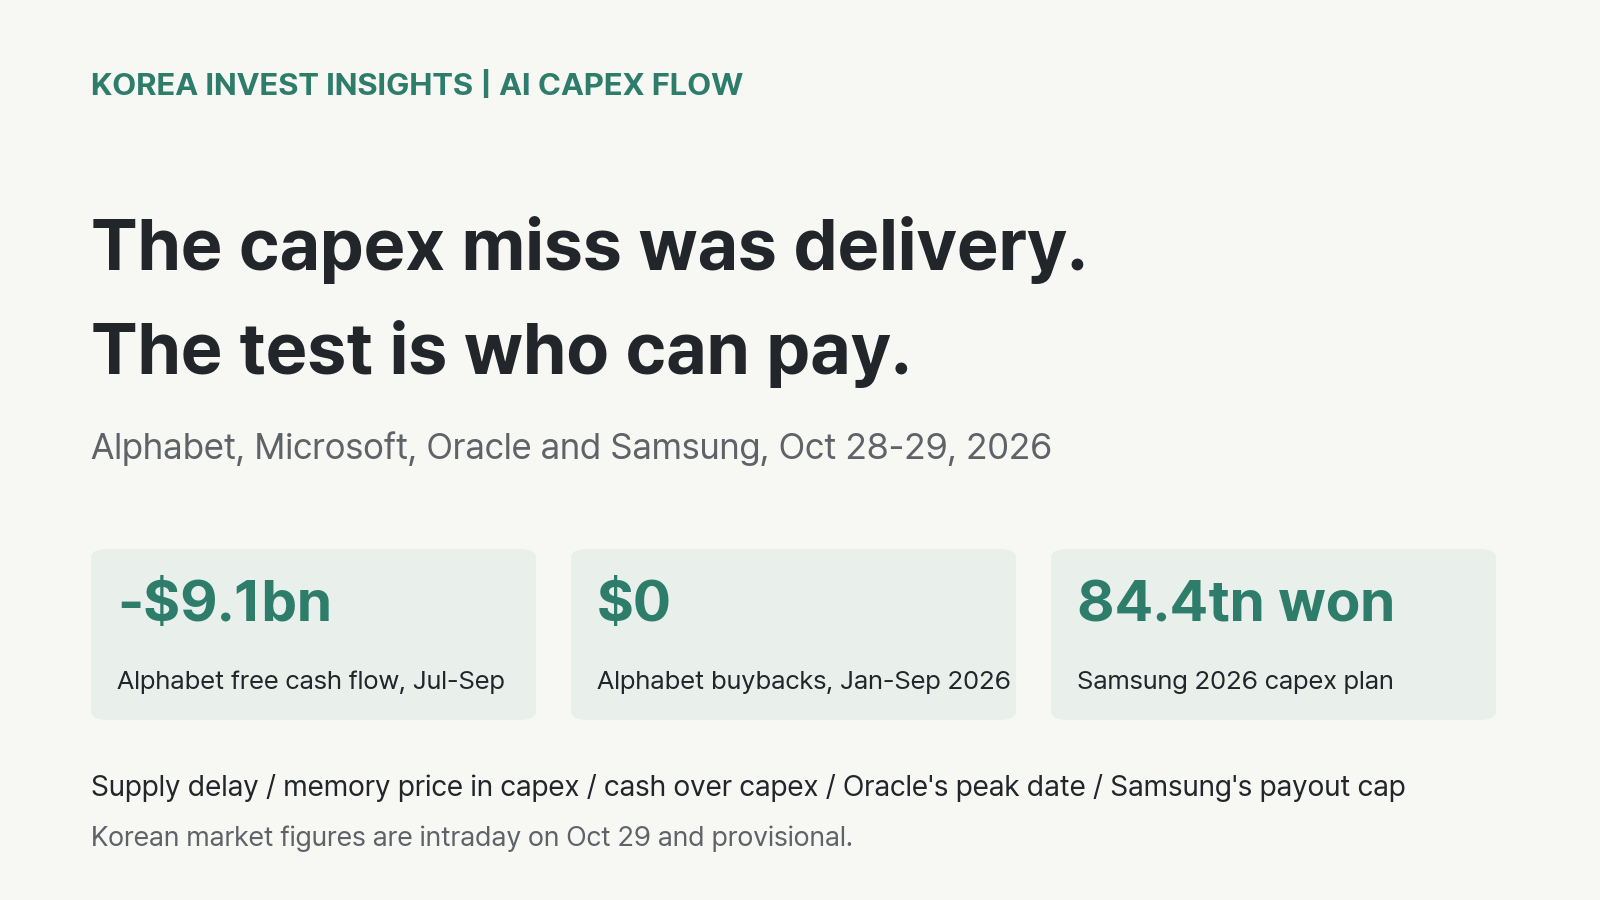
Alphabet and Microsoft spent about $9 billion less than expected because supply arrived late, and both still point higher. Investors priced cash and sold Alphabet. In Seoul, a payout bound by Samsung's own capex turned the market.
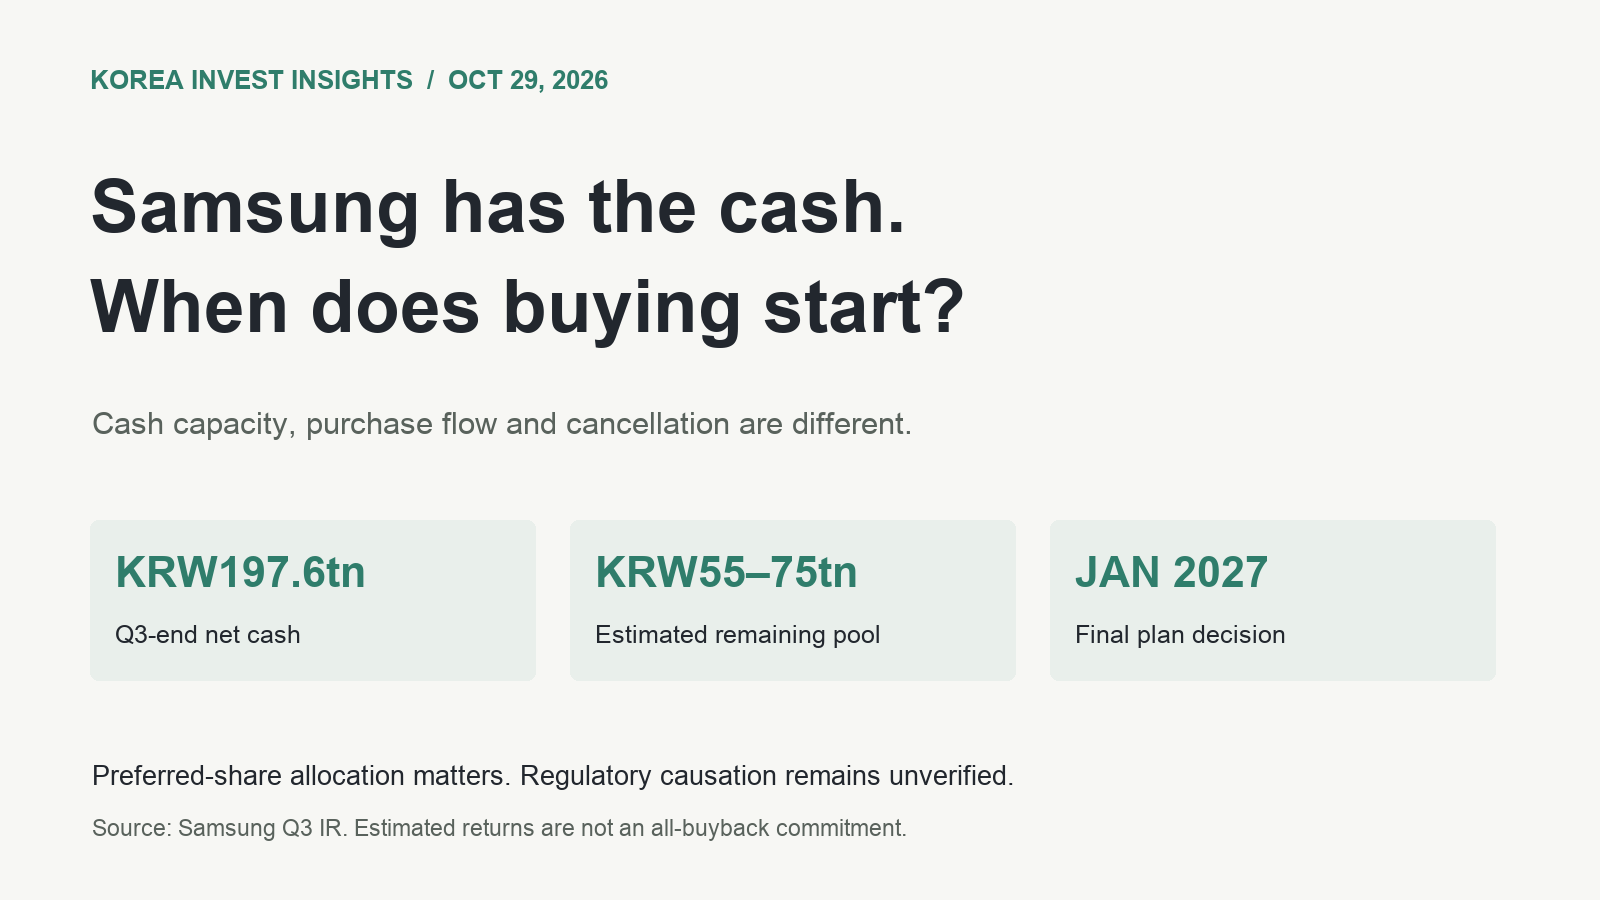
Samsung's KRW55–75tn remaining return pool is an estimate, not a buy order. The January decision was already scheduled. Timing, preferred-share allocation and the dividend record date change the interpretation.
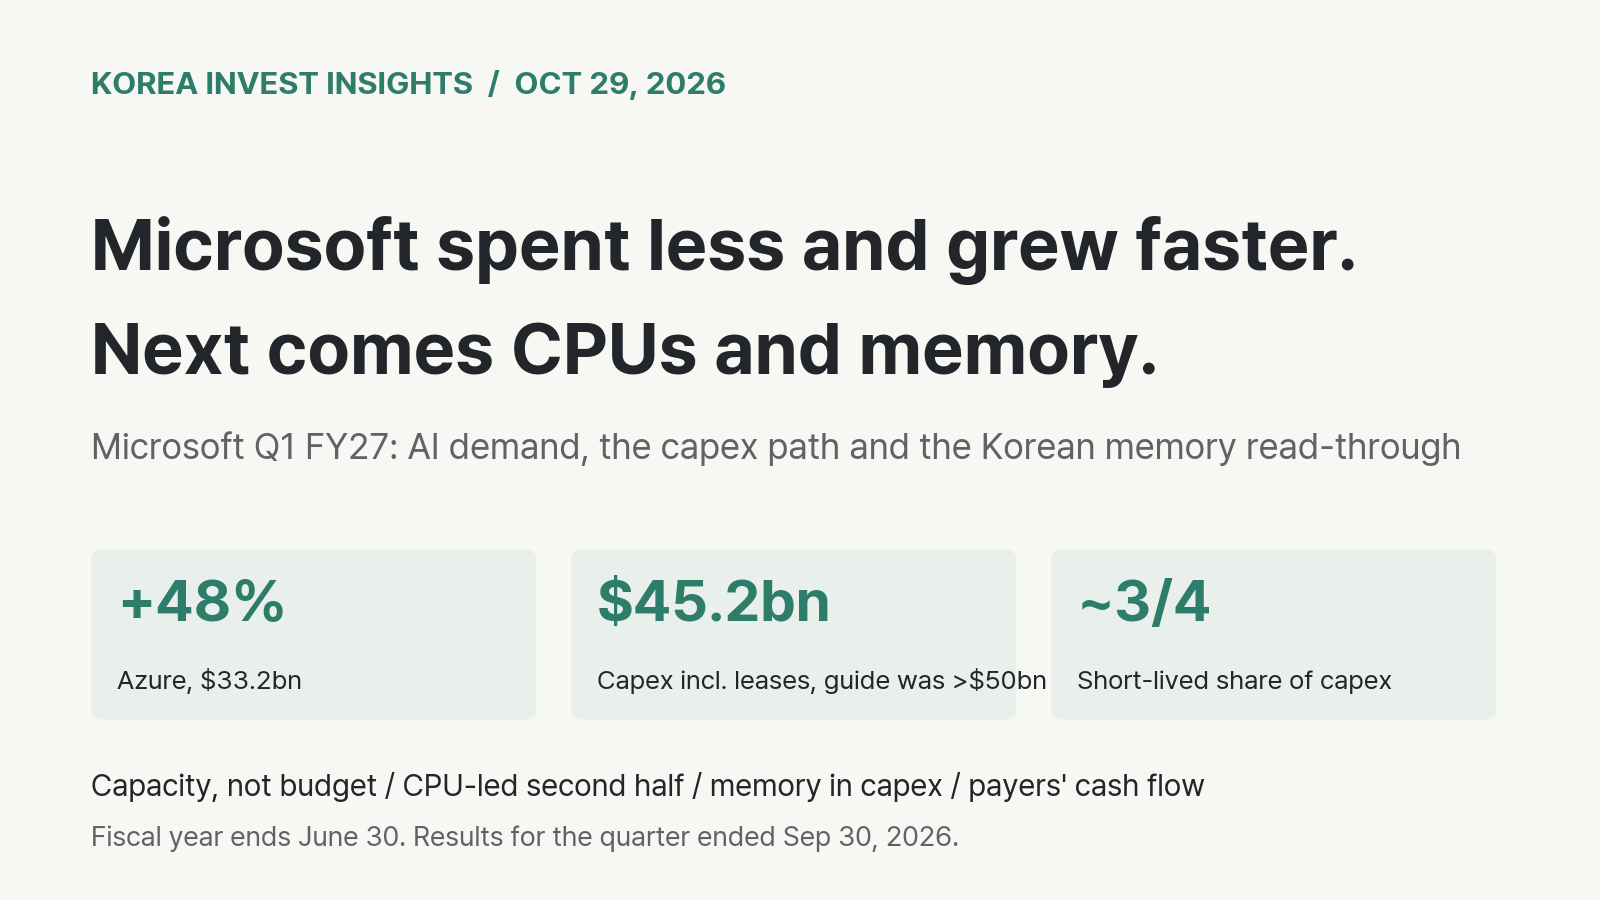
Microsoft's capex came in about $5 billion below its guide because partners delivered capacity late, yet Azure grew 48%. The second-half wave is led by CPUs and inflated by memory prices. For Korean memory, the risk has moved from demand to the payers' cash flow.